When it comes to financial planning, many people get confused between term insurance and ULIP (Unit Linked Insurance Plan). Both offer insurance coverage, but they serve very different purposes.
Choosing the right one can make a big difference in your financial security and long-term returns.
Let’s understand this in a simple way.
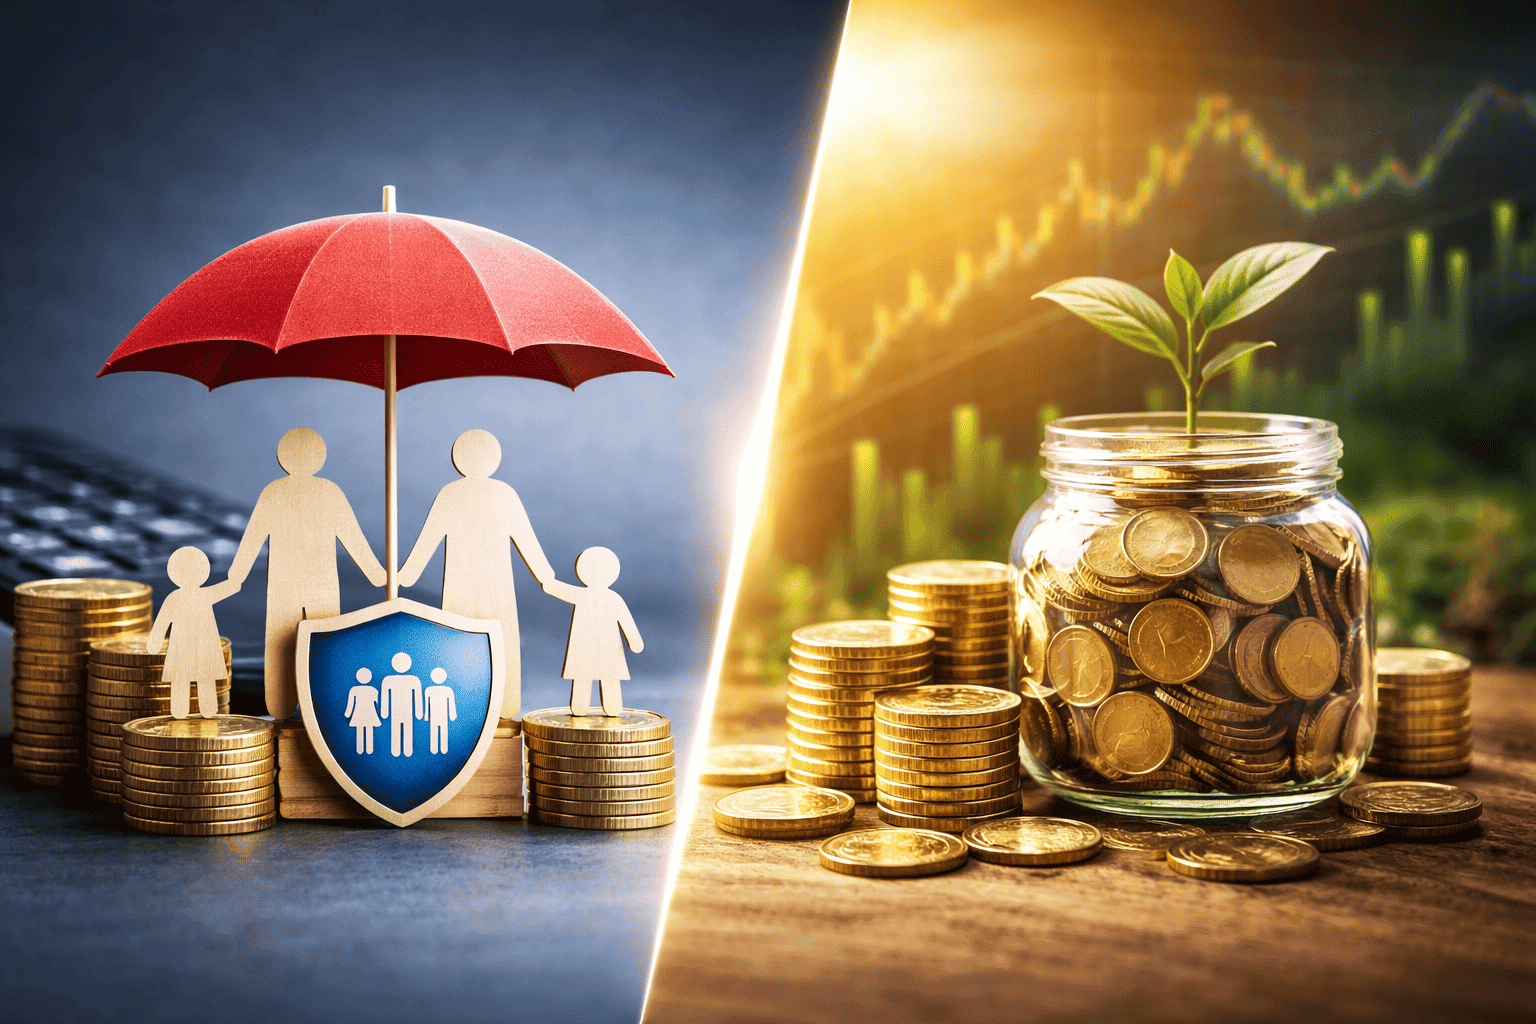
Term insurance is the most basic form of life insurance. You pay a premium, and in return, your family gets a large sum assured in case something happens to you. It is purely designed for protection, not investment.
ULIP, on the other hand, combines insurance and investment. A part of your premium goes towards life cover, while the rest is invested in market-linked funds like equity or debt.
At first glance, ULIPs may seem attractive because they offer both benefits in one plan. But the key question is — does combining both really work in your favor?
Term insurance is simple, transparent, and cost-effective. You can get a high coverage amount at a relatively low premium. This makes it ideal for anyone looking to secure their family’s financial future without complicating things.
ULIPs, however, come with multiple components — charges, fund performance, and lock-in periods. While they do offer investment exposure, returns depend on market performance and may not always be consistent. Also, the cost structure is higher compared to pure investment options.
So, which one should you choose?
If your goal is financial protection, term insurance is clearly the better choice. It ensures your family is financially secure at a very low cost.
If you are specifically looking for investment growth, it is often better to separate insurance and investment. You can take a term plan for protection and invest the remaining amount in mutual funds or other options for better flexibility and potential returns.
Many people make the mistake of mixing insurance with investment without fully understanding the trade-offs. Keeping them separate usually gives you more control, better transparency, and improved outcomes.
At the end of the day, the right decision depends on your financial goals, risk comfort, and long-term planning approach.
The information provided in this article is for educational and informational purposes only and should not be construed as investment, legal or tax advice. Investors should consider their individual circumstances and risk profile before making investment decisions.